Your Premium Is a Stack, Not a Number
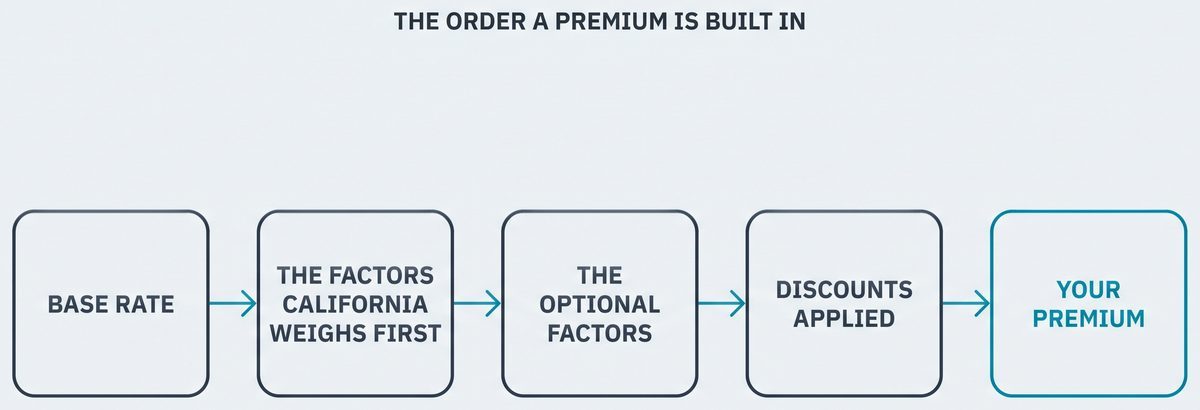
People treat a premium as a single figure that a company either likes or does not. It is not. It is built coverage by coverage, each with its own rate and its own factors, then added together. Once you see the stack, several confusing things become obvious — including why some changes barely register and others move everything.
The layers, roughly in order
- Liability — bodily injury and property damage you cause. Usually the largest single component, and the one most sensitive to your record and your limits.
- Uninsured and underinsured motorist — priced separately, and heavily influenced by where the car lives.
- Medical payments, where carried — typically a small layer.
- Comprehensive — what happens to your car when nobody is driving it. Driven by the vehicle and the location more than by your record.
- Collision — usually the largest physical-damage layer, driven by the vehicle, the deductible and the driver.
- Extras — rental reimbursement, roadside. Small layers.
What this explains immediately
Why dropping a small coverage does not fix a big price. If the number is being driven by liability and collision, removing rental reimbursement is rearranging pocket change. This deserves saying plainly.
For a second reference, the Auto World Insurance Services page on California car insurance cost lays out the same rules with sources.
Why a record affects some layers more than others. Your driving record does its heaviest work in the layers connected to how you drive.
Why the vehicle dominates some quotes. On an expensive car with full physical damage coverage, the vehicle-driven layers can exceed the driver-driven ones.
How to use it when you shop
Ask for the premium broken out by coverage rather than as a total. A good agent will do this without being asked, and it converts a comparison from "which number is smaller" into "where is the difference actually coming from". Two quotes that differ by a lot usually differ in one or two layers, not uniformly.
Where to spend and where to save
The stack tells you honestly: the leverage on price is in the physical-damage layers and the deductible, and the leverage on protection is in the liability layer. Which is why the general shape of good advice is to buy liability generously and manage cost through the deductible — the opposite of what people do instinctively.
Ask us for the breakdown. Seeing your own stack is the fastest insurance education there is.
Get this quoted for your situation
Free quotes from multiple carriers, prepared by a licensed California agent. Two minutes, no obligation.
Get My Free QuoteMore of what callers ask
Can I see the breakdown on my current policy?
Your declarations page shows premium by coverage on most policies. If yours does not, ask the company for it — it is your policy and the breakdown is not confidential.
Which layer do most people over-buy?
In our experience, small conveniences get attention while the liability limit gets left at whatever was selected years ago. That is backwards from where the real exposure sits.
Does removing collision remove the deductible too?
Removing collision removes that coverage and its deductible together — and leaves you paying for your own car after an at-fault crash. It is a legitimate choice on a low-value vehicle and a painful one on anything else.