New: Rate factor explorer — free, and it runs in your browser.

Find out what you would actually pay — from carriers, not a calculator.

Answer a few quick questions and a licensed California agent quotes your exact details across multiple carriers. No estimate in between — the carriers' own numbers, which are the only ones that count.

Why we don't show you an estimate first Any “typical range” we printed would describe someone else — a different record, vehicle, ZIP code and coverage. It would anchor you to a number that was never yours. So we skip it and go straight to quotes built on your actual details.
RateFinder
Real carrier quotes on your own details — about two minutes.Four short steps, then a licensed California agent runs your exact record, vehicle and coverage across multiple companies and calls you with what each one came back with.
  • No estimate in between
  • One agency — never resold
  • No account to create
Quick rate checkStep 1 of 4
Required
What are we insuring?Step 2 of 4
Just the basics — an agent handles the rest on the call.
About the main driverStep 3 of 4
Your date of birth affects the rate more than almost anything else.
Required
Required
Enter a valid date of birth
Required
Where should we send your quotes?Step 4 of 4
A licensed California agent will call with real numbers.
Valid 5-digit ZIP
Valid 10-digit phone
Valid email required
Please check the consent box to continue

$31/mo*  *Where qualifying drivers start — an advertised starting point, not a quote: your number depends on your record, mileage, vehicle and coverage choices.

We don’t promise the lowest rate in the state — nobody honest can. We guarantee something better: we shop multiple carriers for you, and whichever comes back cheapest is the only offer we’ll show you.

Information submitted here goes to a licensed California insurance agency to prepare your quotes. Never sold to third parties.
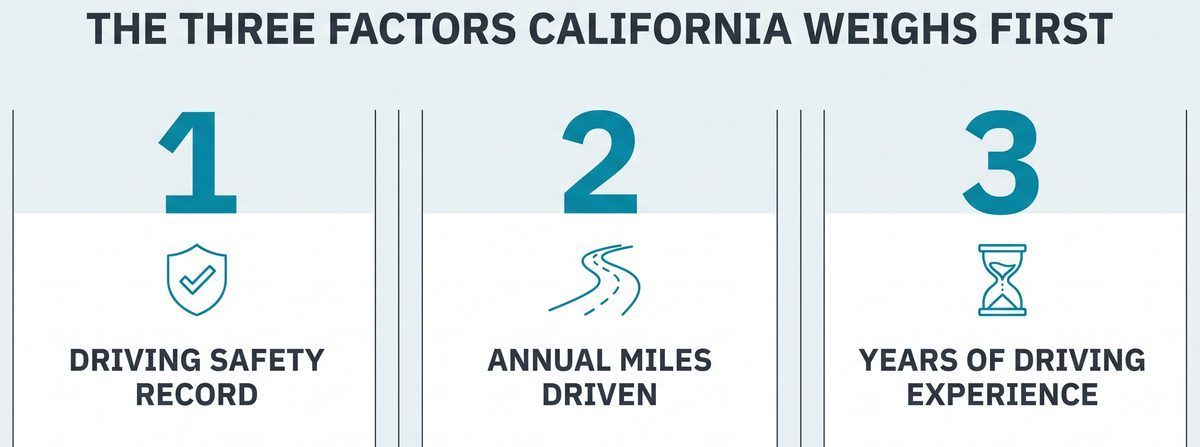
The three factors California requires insurers to weigh first: driving safety record, annual miles driven, and years of driving experience.
Insurance Code section 1861.02, added by Proposition 103, puts these three ahead of everything else an insurer is allowed to consider.
An empty two-lane California highway seen from above, cutting through dry summer hills at dawn.
A driver's hand resting at nine o'clock on the steering wheel of an older sedan during a grey morning commute.
A small brass balance scale tipped slightly out of level beside a stack of plain weights.

Why people send this form instead of collecting quotes one site at a time

Three plain reasons. Nothing here is a statistic and nothing here is a promise about price.

One set of details, several carriers

Each company files its own rating plan with California and weighs your details differently. We’re appointed with several, so your answers get priced by all of them from one form.

A licensed agency, not a lead reseller

Your details go to Auto World Insurance Services, a licensed California broker, and stay there. You are not about to be called by five strangers who bought your phone number.

We explain the number, not just quote it

If a price looks wrong, ask why on the call. Which factor moved it, whether it is a surcharge or a discount you stopped qualifying for, and whether it is worth changing anything.

Your details to real quotes, in three moves

RateFinder's job is to get carriers competing over your actual details, so you find out whether your current rate deserves loyalty or a breakup.

01 / details

Tell us what you drive

Vehicle, drivers, coverage level and your record. These are the inputs carriers actually rate on, so a few minutes here is what makes the quotes comparable.

02 / compare

Agent runs multiple carriers

A licensed California agent quotes your exact details across multiple companies — the part no calculator can do, because final rates come from carrier underwriting.

03 / decide

Keep or switch

You get real numbers side by side. If your current policy wins, keep it — you've lost nothing. If it doesn't, switching usually takes one phone call.
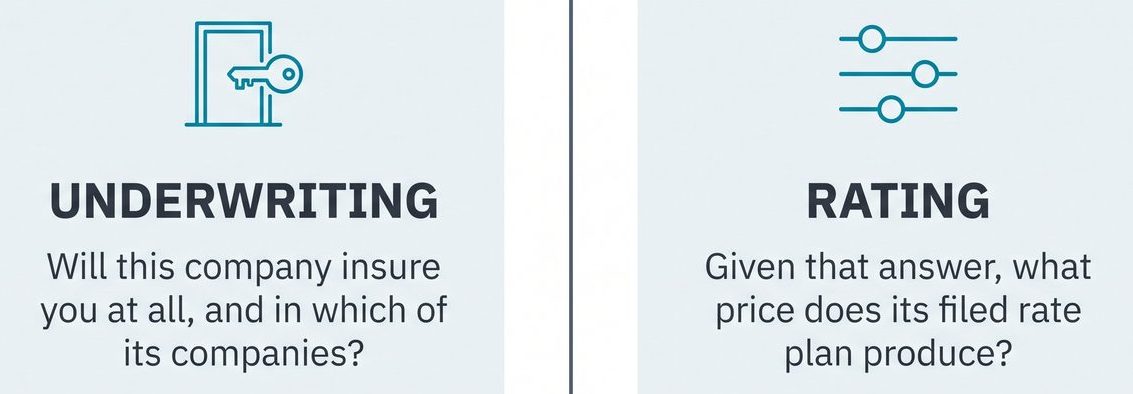
Underwriting decides whether a company will insure you and in which of its companies; rating decides what its filed rate plan then charges.
Two different gates. A price that surprised you was usually decided at the first one.
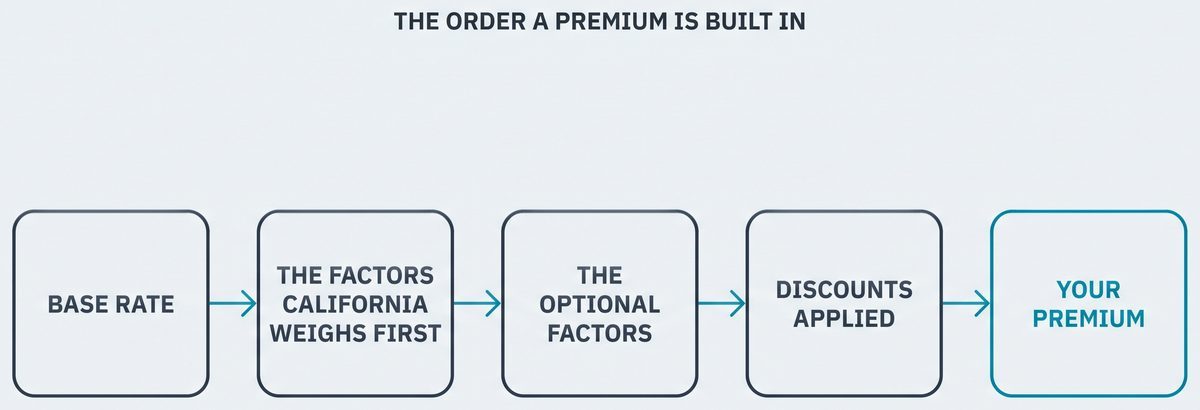
The order a premium is built in: base rate, then the factors California weighs first, then the optional factors, then discounts.
Discounts come last, which is why a discount rarely rescues a rate that went wrong earlier in the stack.
A half-full parking lot in orderly rows photographed from directly above in early morning light.
An open wooden card-index drawer packed with cream index cards and blank raised dividers.
A two-car garage with one sedan parked and the second bay standing empty, door open to morning light.

Fair questions

Will you show me a price before I submit anything?

No, and any site that does is showing you someone else's. A price only means something once it is built from your record, vehicle, ZIP code and coverage choices, and only a carrier can produce it. That is what the licensed agent does with what you enter here.

Why do you need my contact info for real quotes?

Because actual quotes are prepared by a licensed agent and delivered to you directly. Your information goes to one licensed California agency and is never sold to lead brokers or passed to multiple call centers.

Does checking rates affect my credit?

No. Insurance quoting uses a soft inquiry that never affects your credit score.

What Sets Your California Rate — Every Guide

Free tools and help

Rate factor explorer

Pick any factor — credit score, age, ZIP code, prior insurance, marital status — and see whether California lets an insurer use it to set your auto rate, with the law behind it.

Who runs this site

Published by Auto World Insurance Services, a licensed California insurance broker (#6005606). How these pages are written and checked.