Watch a Quote Get Built, Step by Step
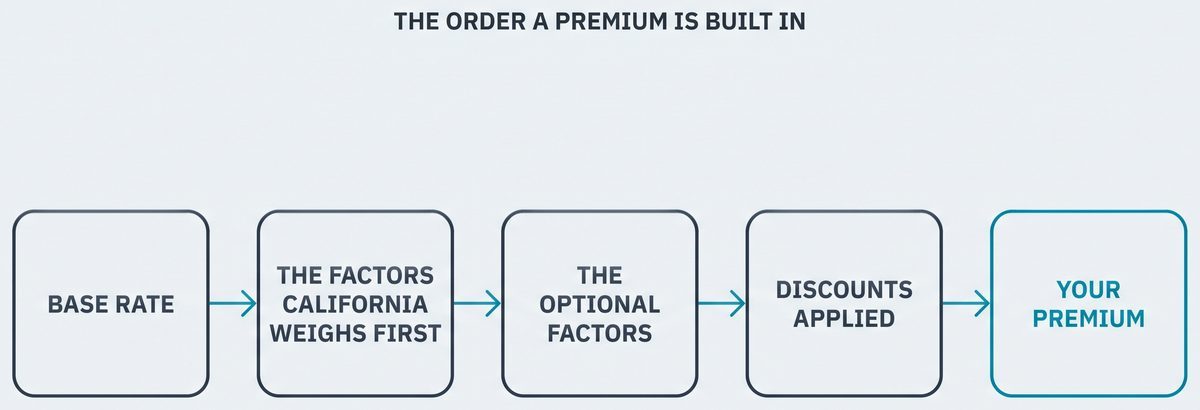
Everything on this site describes one factor at a time. This page runs the whole sequence once, in order, so you can see how the pieces assemble. There are no numbers here on purpose — the point is the order of operations, not an amount we could not honestly give you anyway.
Step 1: Is this company going to write you at all?
Before any pricing, underwriting decides whether the risk fits the company's appetite. If the answer is no, nothing below happens. This is why difficult histories are a matching problem before they are a pricing problem.
The broker behind this page keeps a longer explainer on ITIN auto insurance without an SSN, with the statute links.
Step 2: Which company and tier within the group?
Many insurers write through several companies with different rate levels. Placement happens early and sets the level everything else is applied to.
Step 3: The mandatory three
Driving safety record, annual mileage, years licensed — in that order, weighing more than anything that follows, because Insurance Code section 1861.02 requires it. This is the spine of a California quote.
Step 4: Good driver status
Do you meet section 1861.025? If so, the policy offered must be priced at least 20 percent below your otherwise-applicable rate. This is a status, not a coupon, and it applies before you go looking for anything else.
Step 5: The optional factors
Garaging territory. Vehicle, resolved to a build rather than a badge. Use classification. Number of vehicles and how drivers are assigned to them. Each weighs less than the mandatory three, and each is where companies disagree most.
Step 6: Coverage by coverage
Now the stack is assembled: liability, uninsured motorist, medical payments, comprehensive, collision, extras. Each coverage takes the relevant factors and its own limit or deductible. This is why the same driver can look expensive on one car and reasonable on another.
Step 7: Credits and term
Company-specific discounts are applied, and the total is expressed over the policy term — six or twelve months, which is only a period, not a price.
Step 8: Verification
Records get pulled. If what was entered differs from what is found, the quote changes. That is the whole reason accuracy at step three beats optimism.
Run that sequence honestly and the output is your price at that company — and at the next company, the same sequence with different weights produces a different one. That is exactly what we do for you, across every company we write.
Get this quoted for your situation
Free quotes from multiple carriers, prepared by a licensed California agent. Two minutes, no obligation.
Get My Free QuoteMore of what callers ask
Can I see this breakdown for my own quote?
You can see the inputs and the premium by coverage, which is most of what is useful. The internal factor values are the company's filed plan rather than a customer document, but the inputs are yours to check and correct.
Which step usually explains a surprising number?
Step three and step five, in that order — an inaccurate mileage figure or a vehicle entered at the wrong trim. Errors, far more often than misfortune.
Why can nobody tell me a price before all this?
Because until steps one through six have run against your real details, there is nothing to tell you. Any figure offered before that is advertising, including ours.